


For thousands of Nigerian retirees who spent years waiting for pension increases approved by successive administrations, the failure of government to honour its financial commitments has meant prolonged hardship, uncertainty and a retirement far removed from the security they had worked for.
The Bola Tinubu administration is now seeking to change that experience through the settlement of outstanding pension obligations, the implementation of long-delayed benefits and the introduction of additional welfare programmes for retirees.
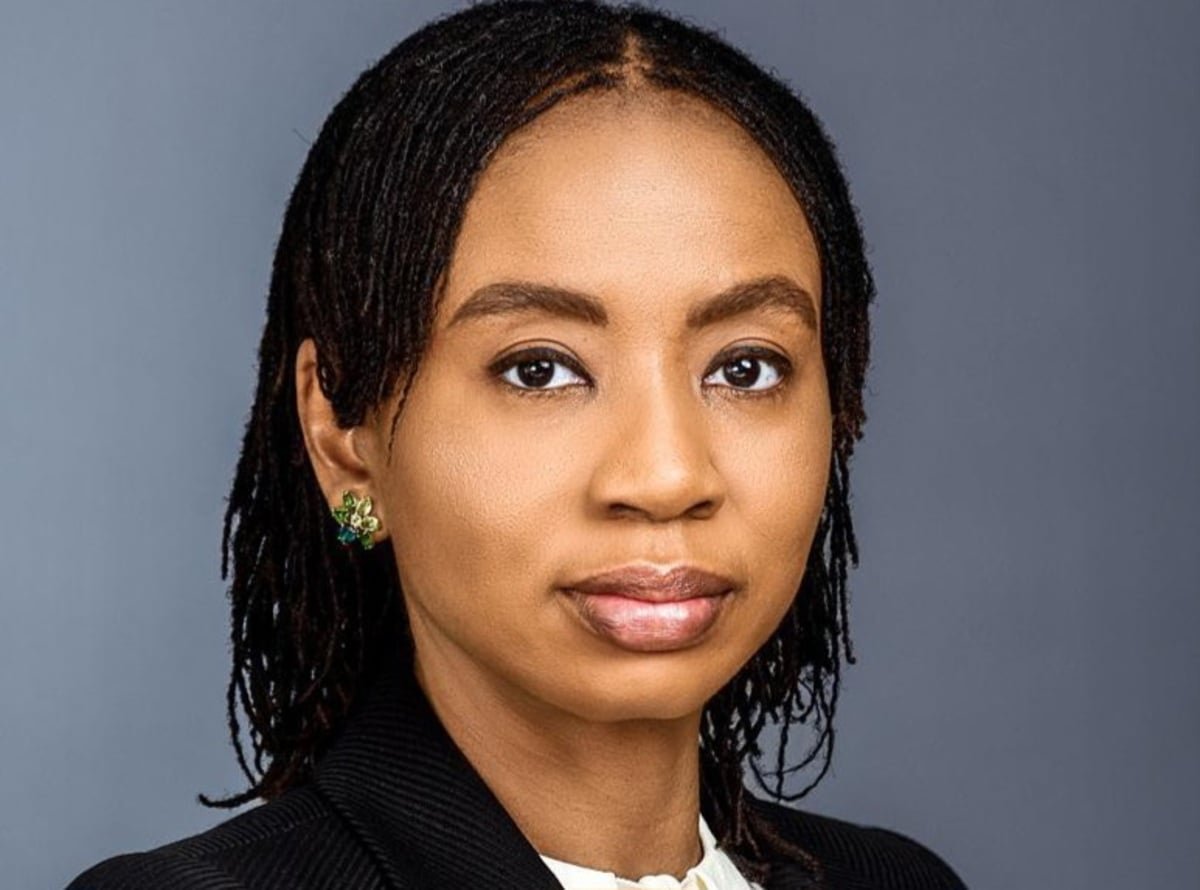
The Director-General of the National Pension Commission (PenCom), Omolola Oloworaran, has outlined how the administration’s interventions are beginning to address longstanding problems in the pension industry, particularly the accumulation of legacy liabilities that prevented many retirees from receiving their full entitlements.
In a scorecard published on her official X handle, Oloworaran said the government had ended what she described as 22 years of broken promises to pensioners, pointing to the release of outstanding funds, implementation of previously approved pension increases and the introduction of healthcare support for vulnerable retirees.
“For 22 years, retirees under the Contributory Pension Scheme were paid in promises. Now they are being paid in cash, healthcare and dignity,” she declared.
The significance of the intervention goes beyond the payment of outstanding liabilities. For retirees, the clearance of pension backlogs could mean improved monthly income, access to benefits that had remained unpaid for years and greater confidence in a system established to guarantee financial security after years of service.
One of the major components of the administration’s intervention is the payment of N758 billion in legacy pension obligations by the Federal Government, according to Oloworaran. The funds have helped address outstanding commitments that accumulated over the years, including pension increases approved by previous administrations but not fully implemented.
The delayed adjustments, which ranged from 37 per cent to 157 per cent, had remained a source of frustration among affected pensioners. Although the increases were approved in 2007, 2010 and 2019, many retirees continued to receive payments that did not reflect the adjustments.
The release of funds to settle these obligations is therefore important because pension increases approved on paper have little practical value to beneficiaries until the necessary financial provisions are made and the revised payments reach their accounts.
For retirees who have spent years struggling with inadequate monthly income, the implementation of the outstanding adjustments represents an opportunity to recover some of the purchasing power lost through inflation and rising living costs.
The administration has also introduced a 22 per cent pension increase as part of its broader effort to improve retirees’ welfare. Although the adjustment does not eliminate the financial difficulties confronting pensioners, it provides additional support at a time when the cost of food, medicines, transportation and other essential services continues to place pressure on household budgets.
Another important development is the activation of the Minimum Pension Guarantee, a provision contained in the Pension Reform Act of 2004 which successive administrations had failed to implement.
Under the arrangement, eligible retirees are guaranteed a minimum monthly pension of N52,500. The provision is intended to protect pensioners whose accumulated retirement savings may not be sufficient to provide an adequate income throughout retirement.
The implementation of the guarantee is particularly significant for retirees who, despite years of contributions, receive relatively small monthly pensions. It introduces a minimum income protection mechanism into the contributory pension system, although its effectiveness will depend on adequate funding and regular review.
The Tinubu administration has also introduced PenCare, a healthcare programme designed specifically for the pension industry. The initiative is expected to provide free essential medical services to about 30,000 vulnerable retirees in its initial phase.
According to Oloworaran, more than N7.3 billion has been accumulated in the PenCare fund, with the programme expected to reduce the financial burden of healthcare on elderly pensioners.
For many retirees, medical expenses can consume a substantial proportion of their monthly pension, particularly as age increases the likelihood of requiring regular treatment and medication. Consequently, the healthcare intervention is expected to complement the financial benefits of pension increases by addressing expenses that often leave retirees with little money for other necessities.
The programme also introduces a broader welfare consideration into pension administration, recognising that retirement security involves more than the regular payment of monthly benefits.
The administration has equally addressed pension obligations under the Nigeria Social Insurance Trust Fund (NSITF), where pensions were increased by an average of 1,173 per cent. Oloworaran described the adjustment as the first in 21 years.
Retired professors have also been placed on pensions equivalent to 100 per cent of their salaries, while exit benefits equivalent to 100 per cent of annual pay have been introduced for the first time.
These interventions are expected to improve the financial position of affected retirees, particularly those whose previous benefits had failed to reflect the length of their service and the changes in the cost of living.
Beyond the payment of outstanding obligations, PenCom has reported improvements in the administrative processes involved in accessing retirement benefits.
According to the director-general, the time required to process retirement benefits has been reduced from 21 months to 48 hours. The improvement is important because delays in processing retirement benefits can leave newly retired workers without immediate access to funds needed to meet their financial obligations.
She also disclosed that the position of accrued pension rights had improved from 21 months in arrears to a 41-month surplus. This indicates a significant improvement in the settlement of outstanding obligations and the commission’s capacity to meet its commitments.
The Pension Protection Fund, which stood at N38.53 billion, has also grown to more than N400 billion. The fund is an important component of the pension system’s safety mechanism, particularly in supporting minimum pension guarantees and protecting eligible beneficiaries against certain risks.
The commission has further recovered more than N40 billion from employers who defaulted on their pension contribution obligations.
The recovery of these funds is significant because employers’ failure to remit pension contributions can undermine the retirement savings of workers. Under the Contributory Pension Scheme, both employers and employees are required to make contributions into Retirement Savings Accounts, and any delay or failure in remittance affects the accumulation of funds available to contributors at retirement.
The clearance of legacy obligations has also extended to state governments. Oloworaran disclosed that about N1.07 trillion in outstanding pension obligations owed by state governments had been paid.
This is particularly important given the financial difficulties confronting many state governments, some of which have struggled to meet pension obligations to former civil servants. Unpaid gratuities and pension liabilities have remained persistent concerns for retired workers across the country.
The interventions have coincided with growth in the pension industry, with total pension assets rising by 55 per cent to N32.21 trillion. The administration has also committed $250 million to infrastructure investment, reflecting efforts to deploy pension resources into productive sectors of the economy while generating returns for contributors.
For the pension industry, the growth in assets presents opportunities to expand investment and strengthen the financial base of the system. However, the increasing value of pension assets must also translate into improved benefits and greater security for contributors and retirees.
Oloworaran maintained that the latest interventions represented a departure from previous administrations, which approved pension increases and made commitments without ensuring that the corresponding funds reached beneficiaries. “What others only promised, this administration has paid,” she said.
The statement reflects the commission’s position that the payment of outstanding obligations marks a decisive break from years of delays that weakened retirees’ confidence in government commitments.
The simultaneous implementation of the Minimum Pension Guarantee and PenCare, according to the PenCom chief, signals the beginning of what the commission describes as Pension Revolution 2.0.
However, the success of the reforms will depend on whether the government can sustain the funding arrangements and ensure that the benefits reach all eligible retirees without unnecessary delays.
The clearance of N758 billion in federal legacy obligations and the reported payment of N1.07 trillion in state pension liabilities represent substantial financial interventions. But the broader challenge of preventing fresh arrears from accumulating remains.
There is also the need to ensure that the N52,500 minimum pension does not lose its value as inflation continues to affect the purchasing power of retirees. Regular reviews, transparent eligibility assessments and reliable funding will be necessary to preserve the benefits of the guarantee.
Similarly, PenCare’s long-term value will depend on the quality and accessibility of medical services available to beneficiaries, as well as the sustainability of its funding.
For pensioners who waited years for approved increases in 2007, 2010 and 2019, the payment of outstanding entitlements offers a measure of relief and renewed hope. But the real test of the Tinubu administration’s intervention will be its ability to maintain the momentum and prevent the pension system from returning to the cycle of unfulfilled commitments.
Ultimately, clearing the legacy backlog is not merely an accounting exercise. It is about restoring the financial security of people who spent much of their working lives in public and private service, with the expectation that their contributions would provide a measure of comfort in retirement.
For millions of retirees facing rising living and healthcare costs, the difference between another government promise and a meaningful pension reform will be measured by the money that enters their accounts, the medical services they can access and the certainty that their entitlements will continue to be paid.


