


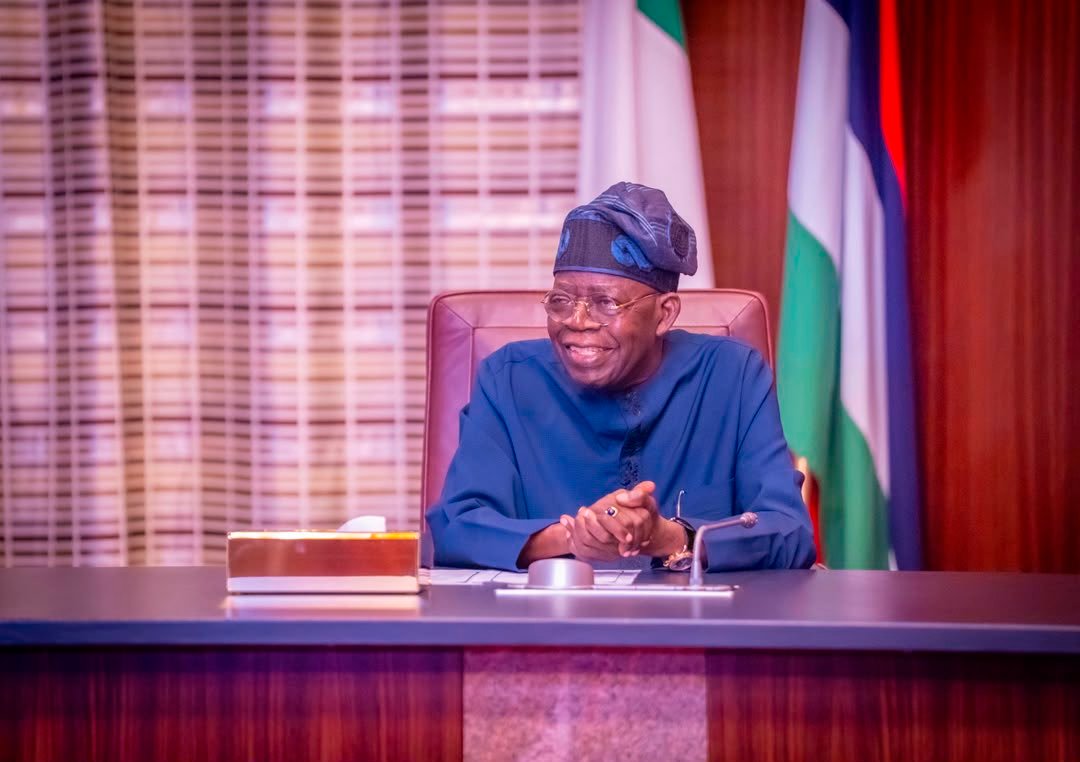
President Bola Tinubu has said Nigeria’s latest economic performance, as outlined in a World Bank report, demonstrates progress from his administration’s reforms, although challenges persist in improving citizens’ living standards.
The World Bank, in its October 2026 Nigeria Development Update, titled Beyond the Federal Purse: How Higher Revenues Reshaped State Priorities, reported that Nigeria’s economy grew by 4.2 per cent in the first half of 2026, compared with 3.9 per cent recorded during the same period in 2025.
The report also indicated that the country’s poverty rate had stabilised for the first time since 2019, with a gradual decline projected as economic growth outpaces population growth.
Tinubu, in a statement issued on Sunday by his Special Adviser on Information and Strategy, Bayo Onanuga, said the findings reflected the impact of the removal of petrol subsidy, foreign exchange market reforms and tighter fiscal management.
The World Bank projected that Nigeria’s economic growth would average at least 4.4 per cent between 2026 and 2028.
On inflation, the report noted that the rate declined from 27.6 per cent in January 2025 to 15.2 per cent in December 2025. However, rising global fuel prices associated with the conflict in the Middle East have slowed further disinflation.
The bank expects inflation to moderate to about 12 per cent by 2028.
Nigeria’s external position also strengthened, with the current account surplus rising to $12bn, equivalent to seven per cent of gross domestic product, in the first half of 2026, up from $8.6bn in the corresponding period of the previous year.
External reserves increased from $45.5bn at the end of 2025 to $53.8bn by the end of August 2026.
The report attributed the improvement in government finances partly to reforms introduced since 2023, which increased federation revenues by 69 per cent in real terms between 2023 and 2025. State governments were identified as the biggest beneficiaries of the additional revenue.
Consequently, states increased capital expenditure by 151 per cent in real terms during the period, directing much of the spending towards roads, transportation, agriculture, energy and housing.
According to the report, 29 of 33 states shifted spending towards economic infrastructure, while real social spending per person increased in all but one state.
Internally generated revenue also grew in real terms in 31 of 35 states, while 21 states reduced their debt-to-GDP ratios between 2021 and 2025.
Nigeria’s overall public debt is projected to decline from 40 per cent of GDP in 2025 to 38.1 per cent in 2026.
Reacting to the findings, Tinubu said the reforms had created greater fiscal space for governments at all levels to invest in development, but acknowledged that more needed to be done to ensure Nigerians felt the benefits.
“The dividends of reform are becoming visible. But more work remains to ensure they fully translate into better living standards for every household, starting with lower food prices and decent jobs for our young people,” he said.
The President said his administration would expand targeted cash transfers, which he said had reached more than 10 million households.
He also pledged to accelerate the deployment of compressed natural gas, improve agricultural productivity and expand access to affordable healthcare and quality education.
Tinubu urged state governments to manage their increased revenues prudently and prioritise projects that directly improve living standards, particularly in healthcare and education.
He reaffirmed his commitment to sustaining the reforms under the Renewed Hope Agenda, saying the administration would focus on inclusive growth and ensuring that the benefits of economic recovery reached Nigerians across the country.


