


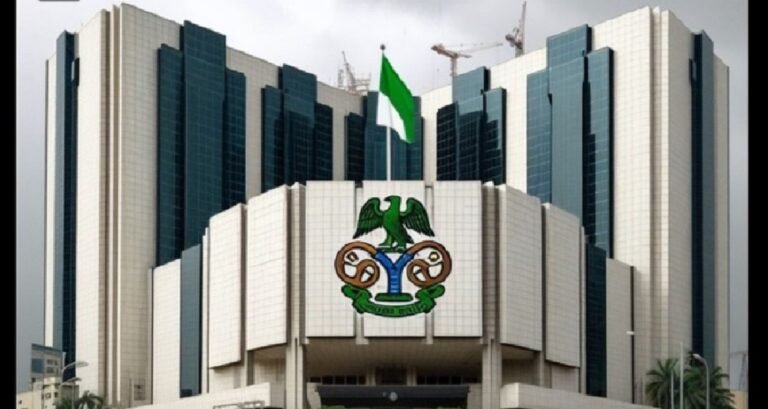
Despite the Federal Government’s insistence that its policies and programmes are yielding desired results, a report by the Central Bank of Nigeria (CBN) is pointing to the financial pressures that continue to confront households across the country.
According to the CBN’s Second Quarter 2026 Economic Report, households in the country are facing persistent inflationary pressures and high borrowing costs, with more Nigerians increasingly relying on credit to meet their financial obligations.
The report showed that Nigerians’ outstanding personal loans increased by an estimated N58.5 billion in the second quarter of 2026, reaching N1.99 trillion at the end of June.
The personal loans rose by 3.03 per cent from approximately N1.93 trillion recorded at the end of March.
The development came as total consumer credit increased by 3.26 per cent to N3.17 trillion from N3.07 trillion in the preceding quarter, representing an increase of about N100 billion within three months.
The CBN stated, “Consumer credit outstanding increased by 3.26 per cent to N3.17tn, from N3.07tn in the preceding quarter. The increase reflected growth in both retail and personal loans, which rose by 4.10 per cent and 3.03 per cent, respectively.”
According to the report, personal loans accounted for 62.87 per cent of total consumer credit, while retail loans constituted the remaining 37.13 per cent.
This means that nearly N63 out of every N100 owed by consumers to financial institutions was classified as personal borrowing, highlighting its dominance in the consumer credit market.
Retail loans also increased by approximately N46.5 billion to N1.18 trillion at the end of June, compared with an estimated N1.13 trillion in March, representing quarterly growth of 4.10 per cent.
Although retail loans recorded a faster percentage increase, personal loans contributed more to the outstanding stock of consumer credit.
The figures are significant because they provide an insight into the financial behaviour of Nigerian households at a time when the cost of living remains a major concern.
While increased access to credit can help individuals manage temporary financial difficulties and meet important obligations, a growing dependence on borrowing to finance everyday consumption raises questions about the strength of household incomes and the ability of borrowers to repay their debts.
For the average Nigerian, the implication is that access to loans may be increasing, but the ability to service such borrowing remains a major consideration.
The increase in personal borrowing occurred amid renewed inflationary pressures, which continued to affect household purchasing power.
The CBN reported that headline inflation rose to 15.91 per cent in June 2026 from 15.38 per cent in March, reflecting increases in the prices of essential goods and services.
The report attributed the development largely to higher energy and commodity prices associated with geopolitical tensions in the Middle East, which increased production and transportation costs.
These conditions placed additional pressure on household expenditure, particularly for consumers whose incomes had not increased sufficiently to offset rising prices.
However, the report did not establish whether the increase in personal loans was driven primarily by household financial difficulties, consumption needs or improved access to credit. The rise in outstanding loans should therefore not automatically be interpreted as evidence that every borrower is experiencing financial distress.
What it does show, however, is that the volume of credit owed by households is increasing at a time when many Nigerians are struggling to maintain their standard of living.
The growth in consumer borrowing also occurred despite elevated lending rates in the banking sector.
According to the CBN, the average prime lending rate declined marginally to 19.01 per cent in Q2 from 19.37 per cent in the preceding quarter.
In contrast, the maximum lending rate increased slightly to 34.37 per cent from 34.34 per cent, indicating that borrowing remained expensive for some categories of bank customers.
Although these rates reflect broader banking sector lending conditions rather than specific personal loan charges, they provide an indication of the financing environment confronting borrowers.
For an average salary earner or small business owner, borrowing at such rates could mean committing a substantial portion of future income to repayment. This becomes more difficult when monthly earnings are already stretched by food, transportation, electricity, rent, healthcare and school fees.
A borrower who takes a loan to meet an immediate household need may eventually find it difficult to repay when another financial obligation arises. In such circumstances, some individuals may resort to additional borrowing to settle existing debts, creating a cycle of indebtedness that further weakens their financial position.
Shift from productive borrowing to consumption
A recent report by Enhancing Financial Inclusion and Advancement (EFInA), titled 2026 Access to Financial Services in Nigeria Survey, provides further insight into the changing borrowing behaviour of Nigerians.
The survey noted that four in every 10 Nigerians borrowing from formal financial institutions now take loans mainly for consumption and coping needs, as rising financial pressures increasingly push credit away from productive activities.
The report revealed that 40.8 per cent of formal borrowers used loans for coping and consumption in 2026, up sharply from 31.7 per cent in 2023.
The 9.1 percentage-point increase made coping and consumption the largest purpose of formal credit, overtaking productive enterprise borrowing, which fell from 40.2 per cent to 34.3 per cent during the same period.
Borrowing for household assets also declined from 25.2 per cent to 23.4 per cent.
The report warned: “Coping/consumption purposes rose from 31.7 per cent to 40.8 per cent; productive purpose fell from 40.2 per cent to 34.3 per cent. We need to ensure that credit builds productive capacity and does not produce distress.”
This development raises concerns about the extent to which borrowing is helping Nigerians improve their economic circumstances.
Ideally, access to credit should enable individuals to establish businesses, acquire productive assets, expand existing enterprises and improve their income-generating capacity. However, when a growing proportion of loans is used to meet immediate consumption needs, the opportunity to generate additional income from borrowed funds becomes limited.
For instance, a business owner who borrows to purchase equipment or expand operations may generate additional revenue with which to repay the loan. But an individual who borrows to pay household bills or meet routine consumption expenses may have no additional income to support repayment.
This does not mean that borrowing for consumption is necessarily irresponsible. Medical emergencies, rent, school fees and other unavoidable expenses can make borrowing necessary. However, the increasing share of credit going into these areas suggests that many households have limited financial buffers to absorb unexpected expenses.
More Nigerians accessing formal credit
The EFInA survey also showed that formal credit use increased from six per cent of adults in 2023 to 10 per cent in 2026, with about 11.9 million Nigerians borrowing from regulated providers.
When informal sources were included, 36 per cent of adults had access to some form of credit.
Credit use among informally employed Nigerians tripled from five per cent to 15 per cent, while borrowing among people aged 18 to 35 rose from four per cent to 10 per cent.
Business owners recorded an increase from four per cent to 10 per cent, while farmers rose from two per cent to six per cent.
The figures indicate that access to formal borrowing is gradually extending beyond traditional salaried workers to include young Nigerians, informal sector operators and people engaged in agricultural activities.
However, the expansion of credit access does not necessarily translate into improved financial well-being. EFInA’s broader findings showed that only about 25 per cent of Nigerian adults were financially healthy in 2026, despite significant progress in financial inclusion.
For policymakers and financial institutions, the challenge is therefore not just to make loans available but to ensure that borrowing helps improve the financial circumstances of individuals and households.
The CBN and other regulators also need to pay attention to responsible lending, transparent interest charges and effective consumer protection, particularly as digital lending platforms make it easier for Nigerians to access loans.
Ultimately, the increase in personal loans to N1.99 trillion is another indication of the financial pressures confronting Nigerian households. While access to credit provides an important financial option, the growing reliance on borrowing for everyday needs raises questions about disposable incomes, purchasing power and the sustainability of household finances.
For the average Nigerian, the real concern is not simply how much credit is available but whether earnings are sufficient to meet daily expenses, repay existing loans and still leave enough money to maintain a decent standard of living.
Unless household incomes improve alongside access to credit, increased borrowing may offer temporary relief without addressing the underlying financial difficulties confronting millions of Nigerians.


