


The United Kingdom and Nigeria are stepping up cooperation to tackle money laundering, terrorism financing, fraud and other forms of illicit financial activity, with both countries seeking to strengthen intelligence sharing and deepen collaboration between government agencies and private-sector institutions.
The renewed partnership, built around financial intelligence, public-private cooperation and cross-border engagement, is expected to support Nigeria’s efforts to improve its capacity to detect suspicious transactions, trace illicit funds and disrupt financial networks operating across national borders.
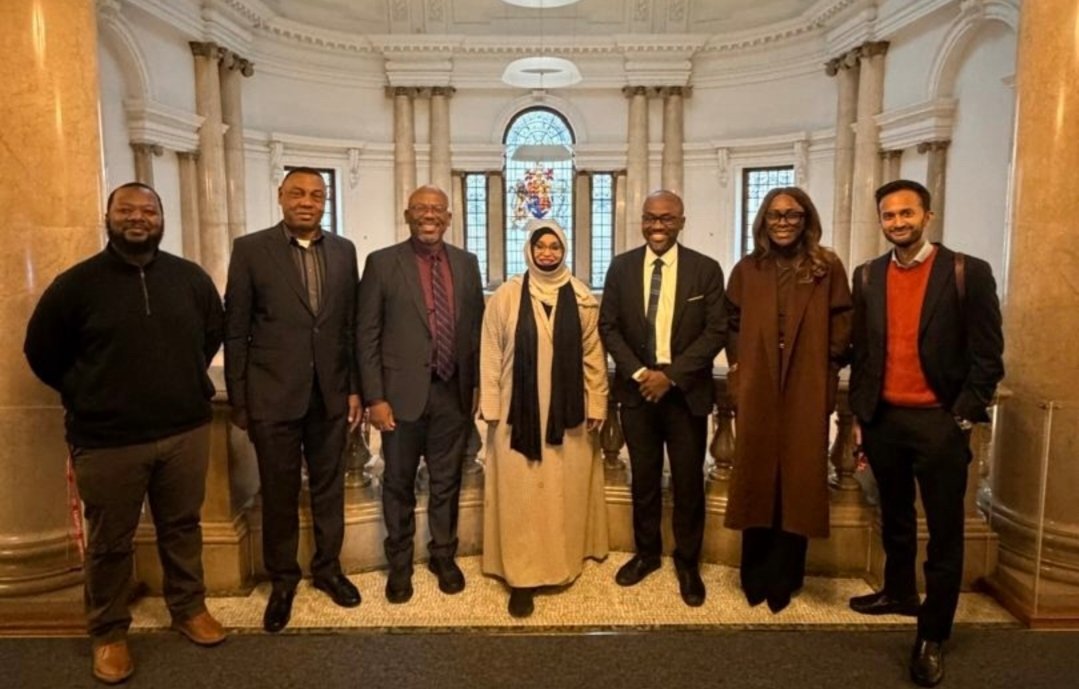
The development followed a series of high-level engagements by a Nigerian delegation in the United Kingdom, where officials held discussions with British financial intelligence, law enforcement, regulatory and government institutions on emerging threats and practical ways of strengthening cooperation.
The Nigerian delegation was led by Hafsat Bakari, Chief Executive Officer of the Nigerian Financial Intelligence Unit (NFIU), and included representatives of the Central Bank of Nigeria (CBN), Nigeria Data Protection Commission (NDPC), Nigerian Communications Commission (NCC), as well as stakeholders from the banking and telecommunications sectors.
The participation of regulators and private-sector representatives reflects the growing recognition that tackling illicit finance requires more than the efforts of financial intelligence agencies and law enforcement institutions.
Banks, telecommunications companies and other financial service providers occupy important positions in the financial system because they process transactions, maintain customer records and operate platforms that can be exploited by individuals and networks seeking to conceal the origin or movement of illicit funds.
A major highlight of the visit was the engagement with the United Kingdom’s Joint Money Laundering Intelligence Taskforce (JMLIT), a public-private partnership that brings together law enforcement agencies, regulators and private-sector institutions to identify and respond to financial crime threats.
Working sessions with JMLIT and UK Finance provided opportunities for both countries to exchange expertise on financial intelligence, information sharing and collaborative approaches to identifying suspicious financial activities.
The engagement is particularly important as financial crimes increasingly involve multiple jurisdictions, complex corporate structures, digital transactions and intermediaries that make it difficult for individual institutions to identify the full extent of illicit financial networks.
Through coordinated intelligence sharing, financial institutions can identify suspicious patterns that may not be visible when information is examined in isolation, while government agencies can use the information to support investigations and other enforcement actions.
The discussions also provided support for Nigeria’s plan to establish the Joint Financial Intelligence Cooperation (JFIC), a Nigerian-led public-private partnership designed to strengthen cooperation between government institutions and private-sector stakeholders.
Anchored on trust, effective governance and technology-enabled cooperation, JFIC is intended to improve the collective ability of participating institutions to identify and respond to money laundering, fraud, terrorism financing and other illicit financial activities.
The initiative is expected to provide a more structured platform for exchanging relevant intelligence, identifying emerging financial crime patterns and improving coordination between institutions that may otherwise operate within separate regulatory and operational frameworks.
For Nigeria, the proposed arrangement represents an effort to build on existing financial intelligence structures by encouraging greater participation from the private sector in detecting and responding to financial threats.
The JMLIT model is particularly relevant to Nigeria’s proposed arrangement because it demonstrates how public and private institutions can work together to identify financial crime patterns that may otherwise escape detection.
Established in 2015, the British taskforce operates under the National Economic Crime Centre (NECC) of the National Crime Agency (NCA). Its expanded JMLIT+ network has more than 200 members drawn from law enforcement, regulators, financial institutions, telecommunications companies, technology firms, virtual asset service providers and other professional organisations.
The effectiveness of the model is reflected in its operational record. According to the NCA, JMLIT+ had helped identify more than 10,700 previously unknown accounts, facilitated the closure of over 8,100 accounts and contributed to more than 391 arrests as of December 2024. It had also helped identify more than £248 million for restraint.
These figures demonstrate the potential value of coordinated intelligence sharing, particularly where financial transactions involve multiple institutions and jurisdictions.
For Nigeria, adapting elements of the model could improve the ability of banks, telecommunications operators, regulators and law enforcement agencies to identify suspicious activities across different platforms.
The discussions in the UK also followed earlier efforts by the NFIU to develop the JFIC framework locally.
In September 2026, the NFIU, with support from the British High Commission and the Convention for Business Integrity, brought together financial regulators, banks, insurance companies, fintech operators, virtual asset service providers and technology firms in Abuja to work on the proposed collaboration.
The engagement was aimed at co-designing a framework that would allow participating institutions to share relevant intelligence, identify emerging threats and strengthen responses to illicit financial flows.
The UK visit therefore represents a further step towards drawing on international experience as Nigeria moves from developing the concept to establishing a functional public-private intelligence-sharing arrangement.
Beyond the JMLIT engagement, the Nigerian delegation held meetings with senior representatives of the National Crime Agency, UK Financial Intelligence Unit (UKFIU), HM Revenue and Customs (HMRC), Foreign, Commonwealth and Development Office (FCDO) and HM Treasury.
The discussions covered operational cooperation, the UK’s Financial Action Task Force (FATF) Presidency, trade-based money laundering, emerging illicit financial risks and opportunities for stronger international collaboration.
Trade-based money laundering remains a major concern for financial intelligence authorities because criminals can exploit international trade transactions to disguise the movement of illicit funds.
This may involve manipulating the value of goods, misrepresenting quantities, using false invoices or conducting transactions through complex networks of companies to conceal the origin and destination of money.
The involvement of HMRC and other UK agencies is therefore significant, given the need to connect financial intelligence with information on international trade, taxation, customs transactions and corporate activities.
The discussions also addressed the changing nature of financial crime, including the use of digital platforms and cross-border financial channels to move proceeds of crime.
Chris Chalmers, Deputy Director, Illicit Finance and Anti-Corruption Department at the FCDO, said the engagements had helped consolidate the longstanding relationship between both countries in tackling financial crime.
“Nigeria and the UK have a deep and long-standing partnership in working together to address illicit financial flows. Illicit Finance harms both of our economies and enables the work of malicious transnational actors,” he said.
He added that the discussions had strengthened cooperation on shared threats and international standards, including public-private partnerships, assuring that the FCDO would continue to support Nigeria in operationalising JFIC.
Bakari said the increasingly interconnected nature of illicit financial networks made international cooperation essential to addressing the threats.
She explained that Nigeria was strengthening its financial intelligence architecture through initiatives such as JFIC, which would enable public institutions and private-sector partners to work more effectively together.
“Our partnership with the United Kingdom provides valuable opportunities to exchange expertise and develop practical solutions that reflect Nigeria’s priorities, strengthen our financial system and translate intelligence into measurable impact,” she said.
Similarly, Marc Brown, NECC Fraud Threat Lead at the NCA, said the partnership between the NECC and NFIU reflected a shared commitment to protecting economic prosperity through a stronger collective response to financial crime.
He said the NCA would continue supporting the NFIU as it develops JFIC, particularly in intelligence sharing, operational effectiveness and efforts to prevent and disrupt networks exploiting both economies.
The renewed engagement comes against the background of Nigeria’s efforts to strengthen its anti-money laundering and counter-terrorism financing framework and improve its standing in the international financial system.
In October 2025, the Financial Action Task Force removed Nigeria from its list of jurisdictions under increased monitoring, commonly known as the grey list, following reforms aimed at addressing identified weaknesses in the country’s anti-money laundering and counter-terrorism financing systems.
The reforms included improvements in financial intelligence dissemination, investigations and prosecutions, beneficial ownership transparency and risk-based supervision of financial institutions and designated non-financial businesses.
Nigeria was also removed from the European Union’s list of high-risk third countries with effect from January 29, 2026, following the international assessment of its progress.
However, removal from these lists does not mean that the threat of illicit finance has disappeared. Sustaining the gains requires effective enforcement, continued institutional reforms and the ability to respond to new methods used by criminal networks.
For Nigeria, the challenge also involves ensuring that intelligence generated by financial institutions translates into actionable information for investigations, prosecutions and the recovery of proceeds of crime.
The proposed JFIC could provide an important platform for achieving this by bringing institutions with different responsibilities and access to financial information into a coordinated framework.
Data protection and governance will also be important to its success, particularly given the participation of the NDPC, financial regulators, banks and telecommunications companies. Effective information sharing must operate within appropriate legal safeguards to protect personal information, maintain confidentiality and prevent the misuse of sensitive financial data.
Ultimately, the success of the UK-Nigeria partnership will depend on how effectively both countries translate their engagements into practical cooperation and measurable results.
For Nigeria, establishing JFIC as a trusted and operational platform could strengthen the ability of public authorities and private institutions to detect suspicious transactions, identify financial crime networks and protect the integrity of the financial system.
Both countries have reaffirmed their commitment to improving intelligence sharing, strengthening public-private partnerships and expanding cross-border cooperation against illicit finance.
The broader objective is to ensure that financial institutions and enforcement agencies are better equipped to identify, trace and disrupt the networks that allow money laundering, fraud and other financial crimes to operate across national boundaries.


