


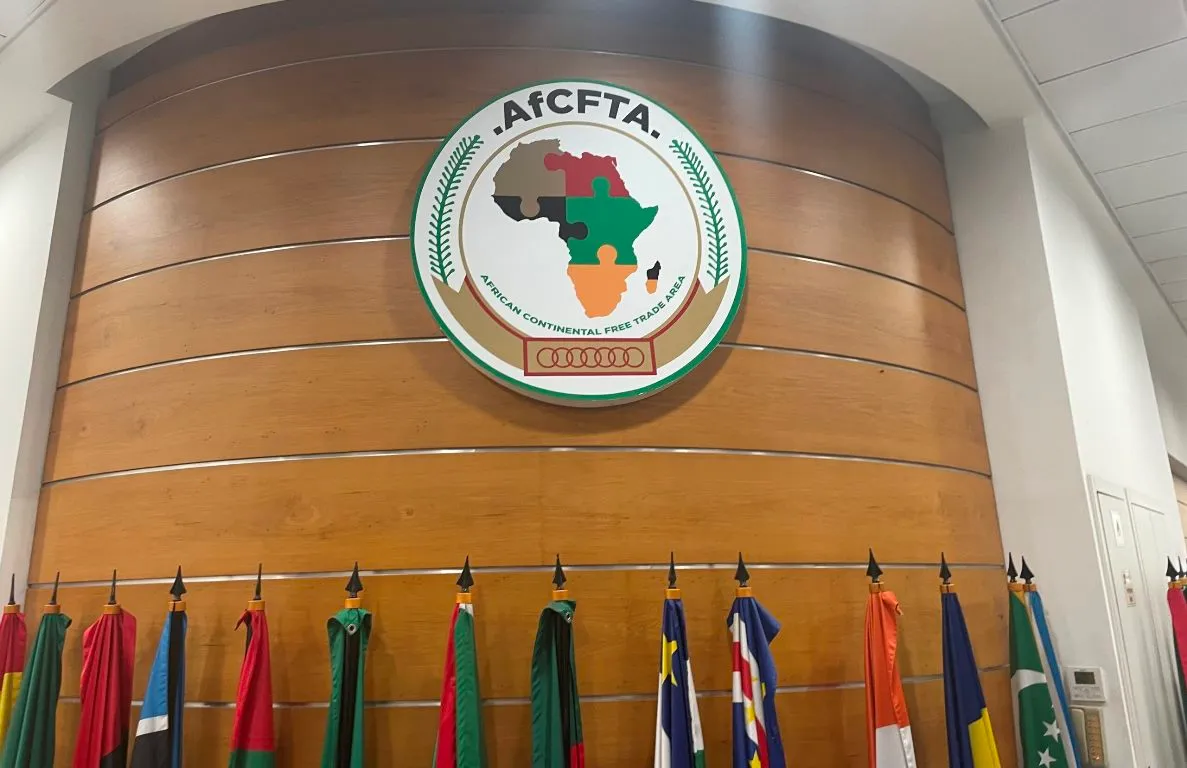
Eight years after signing the African Continental Free Trade Area (AfCFTA) agreement in 2018, intra-African trade still remains a major challenge to the continent, raising questions about the ability of African countries to translate the ambitious trade arrangement into meaningful economic benefits.
Although the agreement was designed to create a single continental market for goods and services, improve the movement of capital and people, and strengthen Africa’s position in global trade, businesses continue to encounter regulatory barriers, expensive cross-border transactions, inadequate infrastructure and cumbersome customs procedures.
According to experts and available reports, intra-African trade remains below 17 per cent of the continent’s total trade, compared with more than 60 per cent in Europe. The disparity reflects the structural difficulties confronting African businesses and the limited progress made towards removing barriers that restrict the movement of goods and services across national borders.
AfCFTA promised access to a market of about 1.3 billion people, with a combined gross domestic product estimated at $3.4 trillion. However, regulatory barriers, fragmented financial systems and costly cross-border payments continue to hinder businesses seeking to expand beyond their domestic markets.
At Moonshot 2026 in Lagos, experts called for urgent reforms to turn the ambition of a single African market into reality, arguing that the success of the agreement would depend less on political declarations and more on practical measures that make it easier for businesses to trade across the continent.
Adetola Onayemi, Chairman of Norebase, highlighted the gap between trade agreements and their implementation, pointing to persistent obstacles at borders, ports and banks.
He called for technology-driven solutions, including standardised business documentation and interconnected digital payment systems, to simplify market entry, reduce transaction costs and make cross-border commerce more efficient.
For many African businesses, the challenge begins before goods leave the country of origin. Differences in customs procedures, product standards, licensing requirements, taxation and business registration rules often make expansion into neighbouring markets difficult.
A company operating in Nigeria, for instance, may have to navigate different regulatory requirements before selling its products in Ghana, Kenya or South Africa. Even where trade agreements provide for preferential access, the practical requirements for obtaining approvals and complying with national regulations can increase the cost and time involved.
Onayemi’s emphasis on technology therefore addresses one of the most important weaknesses in the continental trade arrangement. Digital platforms that allow businesses to verify regulatory requirements, complete documentation and make payments across borders could significantly reduce the administrative burden associated with international trade.
Ultimately, he urged businesses to actively use the AfCFTA to expose bottlenecks and push governments to address them, unlocking the agreement’s potential to boost incomes, expand trade and reduce poverty.
The argument is particularly relevant because AfCFTA cannot succeed through government-to-government commitments alone. Private businesses, manufacturers, exporters, technology companies and financial institutions must become active participants in the process.
However, the difficulties facing intra-African trade extend beyond paperwork and regulatory procedures. Infrastructure remains one of the biggest constraints. Poor road networks, inadequate rail connections, congested ports, unreliable electricity and high transport costs make it expensive to move goods across African countries.
For landlocked countries, the problem is even more pronounced because access to international markets depends heavily on transport corridors and the efficiency of neighbouring countries’ ports and border facilities.
These challenges weaken the competitiveness of African products and make it difficult for manufacturers to benefit from the economies of scale that a continental market is expected to provide.
Another major challenge is the fragmentation of Africa’s financial systems. The continent has more than 40 currencies, with different exchange rate regimes, banking regulations and financial infrastructure. Businesses trading between African countries frequently have to convert their local currencies through the US dollar or euro, increasing transaction costs and exposing them to exchange rate volatility.
This has made cross-border payments expensive and, in some cases, delayed transactions that should ordinarily be completed within hours.
To address this problem, the Pan-African Payment and Settlement System (PAPSS), developed by Afreximbank in collaboration with the African Union Commission and AfCFTA Secretariat, was introduced to facilitate instant cross-border payments in local currencies.
The system is expected to reduce dependence on foreign currencies and international intermediaries, while making it easier for African businesses to receive payments from customers in other African countries. Afreximbank estimated that its full implementation could save the continent more than $5 billion annually in payment transaction costs.
However, expanding the system across different national banking environments, securing participation from financial institutions and ensuring adequate liquidity remain important requirements for its effectiveness.
The challenges also extend to the structure of African economies. Many countries continue to depend heavily on exporting raw materials to markets outside the continent while importing finished products from Europe, Asia and other regions.
This limits opportunities for African manufacturers to develop regional supply chains and exchange intermediate goods within the continent.
According to the United Nations Conference on Trade and Development (UNCTAD), intra-African trade accounts for about 16 per cent of the continent’s total trade. Its 2024 Economic Development in Africa Report also found that only 16 of 54 African countries sourced more than 0.5 per cent of their intermediate goods regionally.
The implication is that African manufacturers still depend significantly on external markets for materials and industrial inputs that could potentially be sourced from other African countries.
AfCFTA was designed to address some of these weaknesses by encouraging countries to specialise in areas where they have competitive advantages, promote regional value chains and increase the movement of manufactured goods across borders.
The World Bank estimated that full implementation of the agreement could increase Africa’s income by seven per cent, equivalent to about $450 billion, by 2035, while lifting 30 million people out of extreme poverty.
However, these benefits are conditional on effective implementation, including reducing tariffs, addressing non-tariff barriers, improving trade facilitation and investing in infrastructure.
Technology funding and Africa’s changing investment climate
Africa’s technology ecosystem is facing a new reality as cheap capital dries up and international investors reassess their exposure to the continent. With funding becoming harder to secure, start-ups are under increasing pressure to demonstrate profitability, financial discipline and sustainable business models.
But does this mark the end of Africa’s tech boom, or the beginning of a more mature ecosystem? The shift could signal a transition from rapid expansion towards building resilient businesses with long-term economic value.
The development is relevant to the AfCFTA debate because technology companies have an important role to play in removing some of the barriers that restrict African trade.
Digital payment providers, logistics platforms, business registration services and supply chain technology companies can help businesses navigate different markets, process transactions and connect with customers across national borders.
However, these solutions require investment, supportive regulations and access to markets. If African start-ups struggle to raise capital, their ability to develop and scale the technology needed to support continental trade could also be affected.
The changing investment environment means technology companies may have to look beyond rapid customer acquisition and prioritise revenue generation, operational efficiency and products that address practical economic problems.
For investors, the focus is increasingly on businesses with clear paths to profitability, strong corporate governance and the capacity to operate across different African markets.
A more disciplined technology ecosystem could ultimately support AfCFTA by producing companies capable of solving real problems in trade, finance, agriculture, transportation and manufacturing.
Governance and investor confidence
The latest Mo Ibrahim Foundation report reveals that nearly half of Africa’s population lives in countries where governance has deteriorated over the past decade. The findings raise concerns about institutional performance, political stability and investor confidence.
The foundation’s 2024 Ibrahim Index of African Governance, covering the period between 2014 and 2023, found that governance progress across the continent had stalled, with security challenges and declining democratic participation undermining improvements recorded in other areas.
According to the report, 52.1 per cent of Africa’s population live in 33 countries where overall governance improved during the period, while the remaining population live in countries where governance performance was worse in 2023 than in 2014.
Weak governance can undermine business environments and slow economic development, making stronger institutions, transparency and accountability essential to securing sustainable growth across the continent.
For AfCFTA, the implications are considerable. Businesses need predictable regulations, functioning public institutions, transparent customs administration and confidence that commercial agreements will be respected.
Political instability, insecurity, corruption and inconsistent government policies can discourage investment and make cross-border operations more difficult. Investors are less likely to commit long-term capital to markets where regulatory decisions are unpredictable or the enforcement of contracts is uncertain.
Security is another important consideration, particularly in parts of West, Central and East Africa where conflicts and insurgency have disrupted transportation routes, agricultural production and commercial activities.
The African Union and national governments must therefore recognise that economic integration cannot be separated from governance, security and institutional reforms.
Ultimately, AfCFTA remains one of Africa’s most ambitious economic projects, but its success will depend on whether governments can move beyond signing agreements to implementing policies that make cross-border business genuinely easier.
The continent needs more efficient ports, modern transport infrastructure, reliable electricity, harmonised regulations and accessible financial services. It also needs stronger institutions capable of enforcing trade agreements and protecting businesses operating across national boundaries.
Businesses, on their part, must take advantage of the opportunities available under the agreement rather than continue to operate largely within domestic markets.
Eight years after the agreement was signed, and nearly six years after continental trading officially commenced in January 2021, Africa cannot afford to allow the promise of a single market to remain largely on paper.
The real test is whether African countries can turn their combined population and economic potential into a functioning market where goods, services, capital and technology move with fewer restrictions.
Until that happens, the continent will continue to trade more easily with the rest of the world than with itself, while businesses and ordinary citizens miss out on the economic opportunities AfCFTA was established to create.


 agreement in 2018, intra-African trade still remains a major chall)